Mastercard and Visa are extending stablecoin technology into the systems that settle card payments between financial institutions, while leaving the consumer checkout experience largely unchanged. Mastercard completed its acquisition of stablecoin infrastructure provider BVNK in August 2026 and has expanded its network’s settlement options to include regulated stablecoins. Visa, meanwhile, is working with Stripe-owned Bridge and Lead Bank on on-chain settlement for card programs. The shift became more concrete in September, when SoFi Bank moved its credit and debit card issuing portfolio to live settlement using its bank-issued SoFiUSD. That portfolio represents more than $25 billion in annualized card volume, a measure distinct from the value settled in stablecoins. Visa separately reported an annualized stablecoin settlement run rate exceeding $25 billion in October. The networks’ initiatives target the back-end movement and reconciliation of funds, including periods when traditional bank settlement rails are unavailable; they do not require merchants to accept cryptocurrency.
StraitsX has opened onboarding for digital payment token providers across more than 100 markets through an expanded card-issuing architecture developed with Visa. Integration documentation published on 26 October 2026 describes a multi-BIN model that combines issuing sponsorship, transaction authorization, compliance screening and fiat clearing. The approach lets participating providers build stablecoin-backed card products while merchants continue to receive conventional fiat payments through Visa’s network. StraitsX says its card gross transaction value rose 40-fold year on year from Q4 2024 to Q4 2025, while cards issued across Asia increased 83-fold. On-chain issuer telemetry recorded monthly card transaction volume of $310 million to $438 million through October 2026. The company’s stated $6 billion annualized card transaction figure is distinct from its cumulative $70 billion in processed stablecoin volume. StraitsX and Visa have also scheduled demonstrations of agentic payments for November 2026.
Stripe confirmed in October 2026 that it plans to expand its Bridge- and Visa-powered stablecoin card issuing program from 18 initial countries to more than 100 by the end of the year. The planned rollout spans Europe, Asia-Pacific, Africa and the Middle East. It follows Stripe’s February 2025 acquisition of Bridge, whose APIs connect stablecoin transfers with fiat accounts and bank payouts. Stripe has also made Open USD available to businesses in Stripe Financial Accounts alongside USDC. Its broader stablecoin infrastructure combines Bridge’s conversion tools with Stripe’s existing payment and treasury network and embedded wallets from Privy. Lead Bank supports the card program as a financial institution partner and BIN sponsor. A separate deployment by Ramp uses Bridge APIs and Privy wallets to let businesses pay vendors in stablecoins using funds from fiat bank accounts. Together, the developments show how Stripe is assembling stablecoin services for business payments, while the planned geographic expansion remains unfinished.
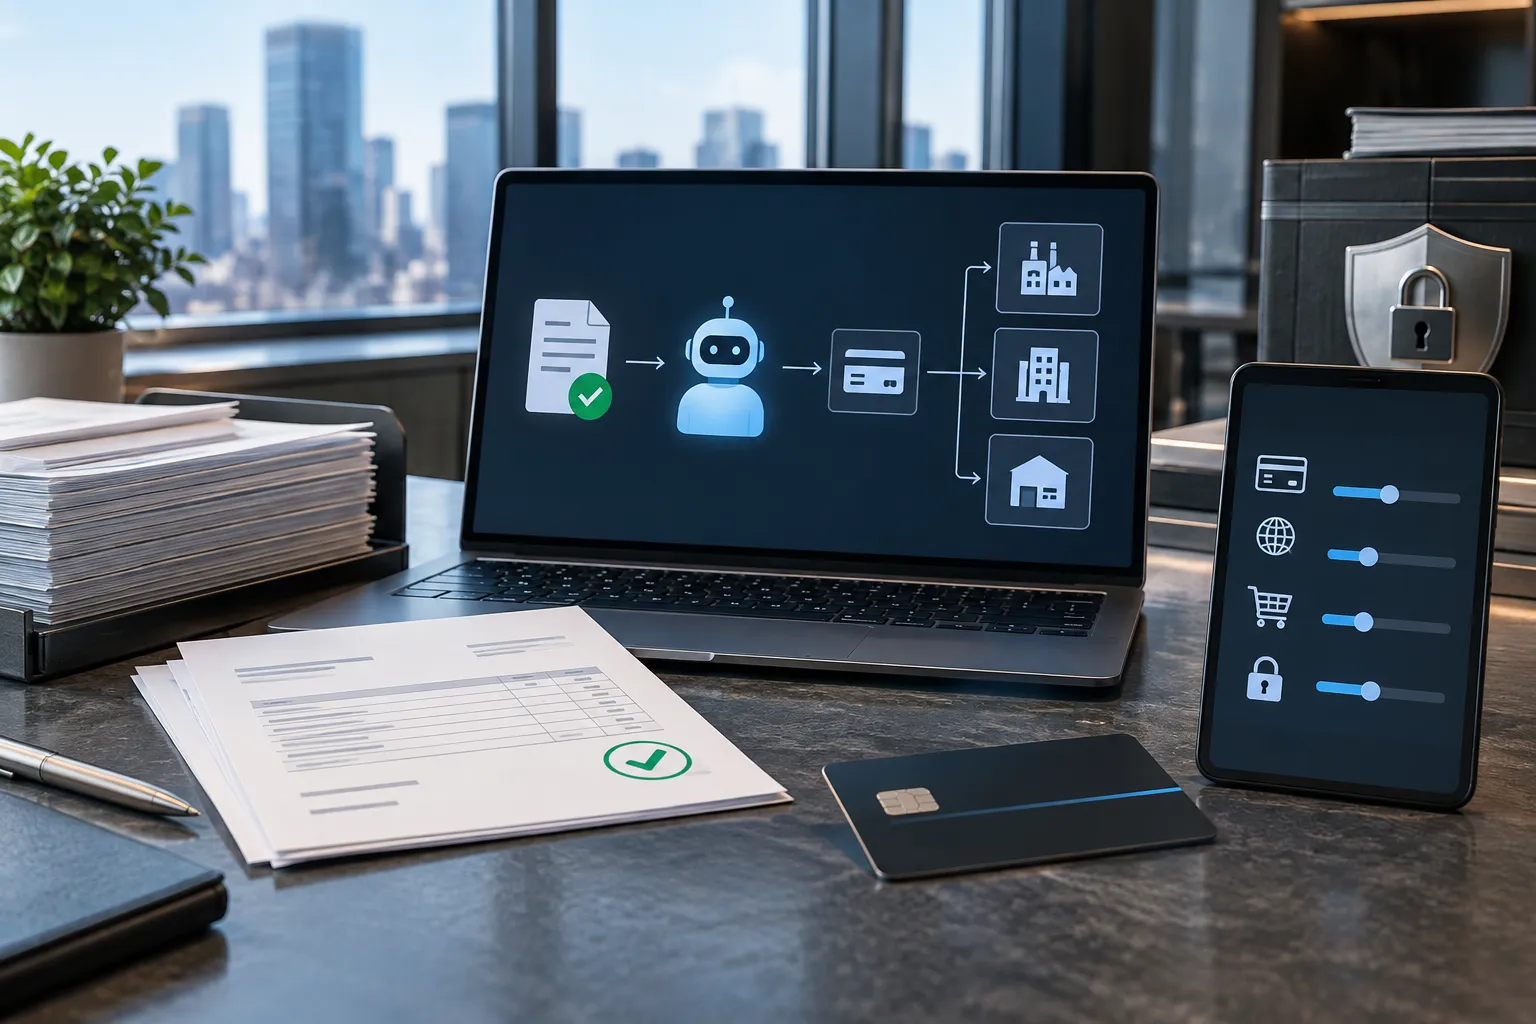
Visa launched a live pilot with BILL and Billtrust at Money20/20 USA in late October 2026 to test end-to-end B2B invoice payments executed by software agents. The agents act on invoices enterprise buyers have already approved; they do not decide which supplier payments to authorize. Visa’s Trusted Agent Protocol and Agentic Directory are designed to authenticate those agents when they access supplier and merchant portals without shared credentials or manual human login. Separately, Visa has put Commercial Payment Controls into production for eligible issuers in supported regions, allowing businesses to set limits and restrictions on corporate spending. The company plans general availability of Commercial Virtual Authentication and Commercial Supplier Validation in 2027 after pilot completion. Its SESA 2.0 analytics platform has identified more than $600 billion in potentially cardable supplier spend. The pilot tests whether approved invoice payments can be executed through automated workflows while preserving buyer-defined controls.
Fireblocks has rejected an Axios report that Visa was in advanced talks to acquire the digital-asset infrastructure company for about $2.5 billion. Fireblocks said the reported discussions were not taking place at present. Visa declined to comment on the claim, while Coinbase separately denied reports that it was considering a bid. None of the companies has confirmed an acquisition process. The reported price would be about 69% below Fireblocks’ $8 billion valuation from its January 2022 Series E funding round. The company generated $124 million in revenue in 2024 but remained unprofitable, and it has initiated plans to cut 60 to 70 jobs amid the rumors. Visa already uses Fireblocks as an institutional client and works with it on an interoperability initiative. Those existing links provide context for the speculation, but do not establish that a transaction is under discussion.
Mastercard and Visa are advancing different approaches to AI-initiated business payments. At Cloudflare Connect, Mastercard demonstrated an agent making nine payments across multiple service providers under one authorized budget. It also opened early developer access to Agent Pay APIs, a sandbox and toolkits. Visa expanded its commercial agentic suite around a BILL and Billtrust pilot, alongside spend analytics and fraud tools. The distinction is how each approach constrains the agent. Visa’s pilot lets an agent pay invoices that buyers have already approved, using its Trusted Agent Protocol to navigate supplier-portal security without sharing underlying login credentials. Mastercard is testing controls for machine-to-machine transactions, including signed vouchers, agent verification and a score intended to estimate whether an incoming transaction was AI-initiated. Both efforts leave a consequential question for business payments: how responsibility should be assigned when an authorized agent follows its technical instructions but breaches a procurement condition.